

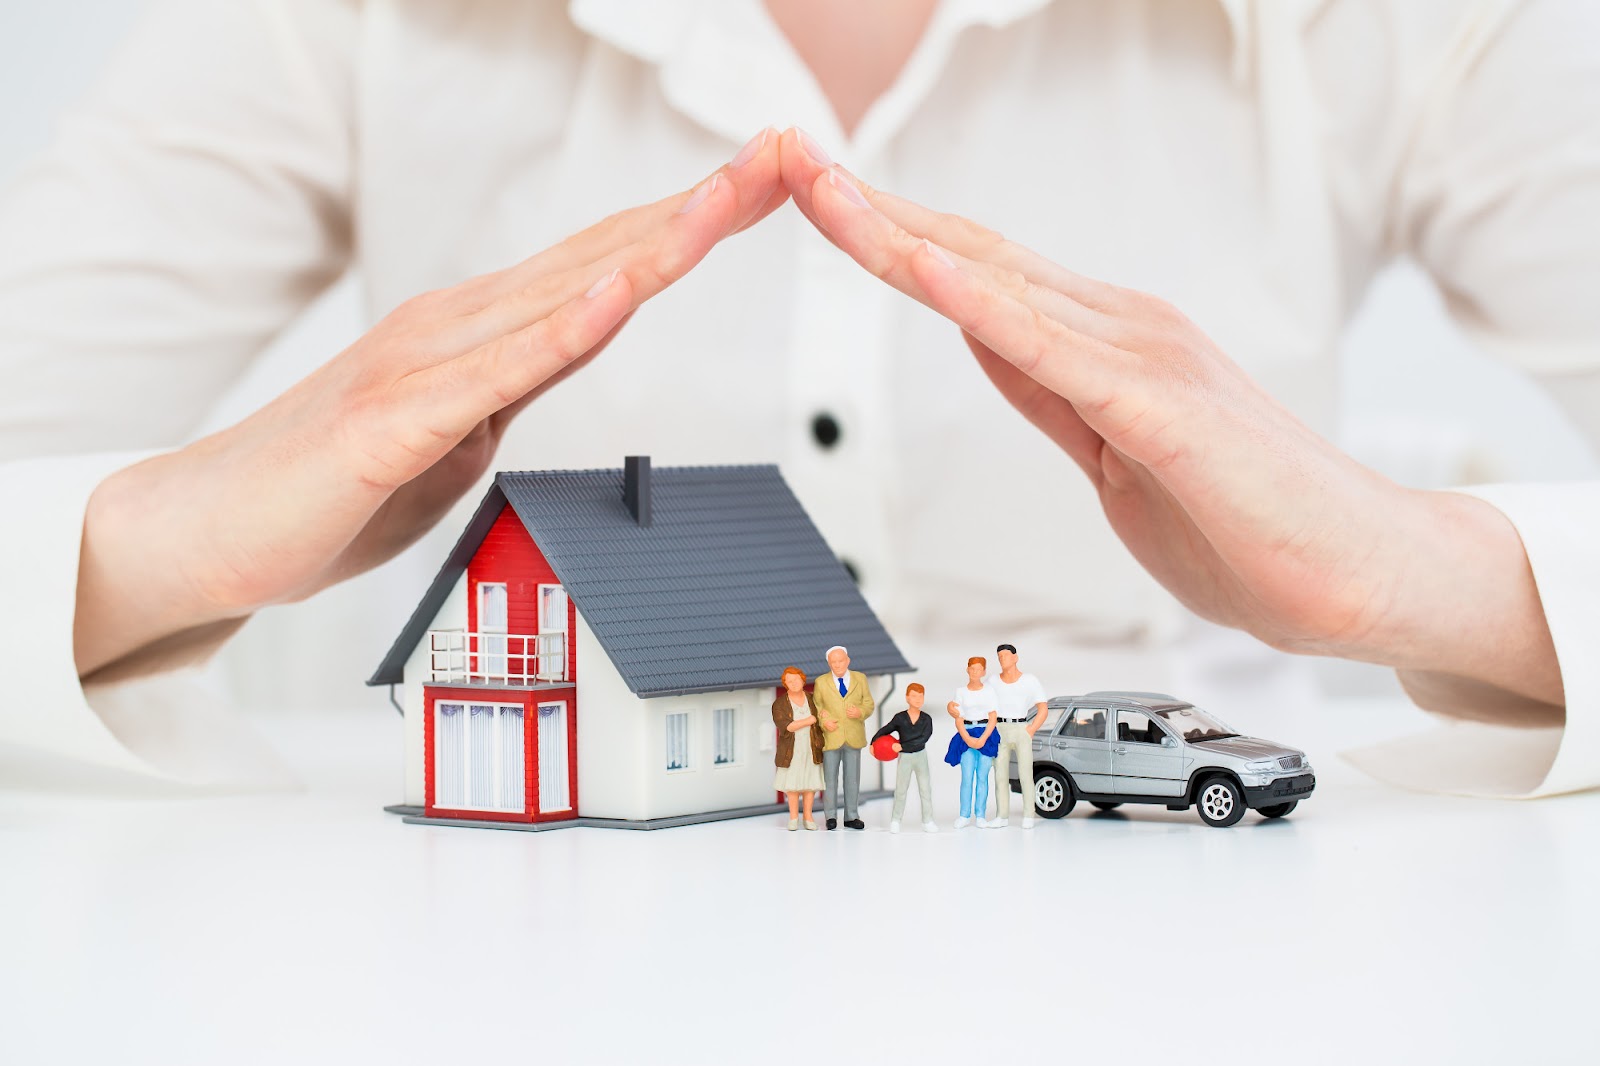
For many people, a home is the largest purchase they will ever make. It is more than a place to live, raise a family, and build memories. It is also a major financial asset that needs to be protected. Unlike stocks, bonds, or other investments, a home is exposed to physical risks every day. Fire, storms, theft, vandalism, water damage, falling trees, liability claims, and other unexpected events can create expensive losses.
That is why understanding how to buy home insurance is so important. A homeowners insurance policy can help protect your property, personal belongings, and financial stability if a covered event damages your home or creates legal responsibility. Without the right coverage, one serious loss could force you to pay repair, replacement, or liability costs out of pocket.
Many homeowners spend a large part of their income on housing and related expenses. An average person may spend 40-50% of their monthly income on housing and utilities. Because so much money is tied to the home, choosing the right insurance policy should not be treated as a quick afterthought.
Home insurance is not only about meeting mortgage requirements. It is about making sure you can recover financially if something goes wrong. The right policy can help pay to rebuild your home, repair covered damage, replace personal belongings, cover temporary living expenses, and protect you from certain liability claims.
Here is how to buy home insurance, compare policies, understand coverage, and choose protection that fits your home, location, budget, and risk level.
What Is Home Insurance?
Home insurance is a contract between a homeowner and an insurance company. You pay a premium, and the insurer agrees to help cover certain losses listed in your policy. These losses may include damage to the structure of your home, damage to personal property, liability claims, and additional living expenses if you cannot live in your home after a covered event.
A standard homeowners insurance policy may include several major types of coverage:
- Dwelling coverage: Helps pay to repair or rebuild the physical structure of your home after covered damage.
- Other structures coverage: Helps cover detached structures such as garages, sheds, fences, or guest houses.
- Personal property coverage: Helps replace belongings such as furniture, clothing, electronics, and appliances.
- Liability coverage: Helps protect you if someone is injured on your property or if you are legally responsible for certain damages.
- Medical payments coverage: Helps cover small medical expenses if someone is injured on your property, regardless of fault.
- Loss of use coverage: Helps pay for temporary housing and extra living expenses if your home is unlivable after a covered loss.
Not every policy covers the same risks. That is why homeowners should review policy limits, exclusions, deductibles, and endorsements before buying coverage.
Make a Shopping List Before Comparing Home Insurance Quotes
Before choosing a homeowners insurance policy, make a clear shopping list of what you need. Buying home insurance is similar to choosing any major financial product. You should not accept the first quote without understanding what it includes, what it excludes, and how it compares to other options.
When investors compare stocks, they often research the market carefully and may use scanners like Trade Ideas to evaluate opportunities. Home insurance deserves the same level of attention. You are protecting a major asset, so the decision should be based on more than price alone.
There is a large market of insurance companies offering different levels of coverage, pricing, discounts, deductibles, and claim support. You should compare quotes from several major insurers and review what each policy actually provides.
When comparing home insurance policies, review:
- Dwelling coverage limits
- Personal property limits
- Liability coverage limits
- Deductible amount
- Covered perils and exclusions
- Replacement cost vs. actual cash value
- Flood, earthquake, or windstorm exclusions
- Available endorsements and riders
- Discounts for bundling or safety upgrades
- Claims reputation and financial strength ratings
The cheapest policy may not be the best policy. A low premium can be attractive, but it may come with a high deductible, lower limits, or important exclusions. If disaster strikes, weak coverage can cost far more than the money saved on premiums.
Compare Deductibles Carefully
A deductible is the amount you pay out of pocket before your insurance coverage applies to a claim. For example, if your deductible is $2,000 and a covered storm causes $15,000 in damage, you would generally pay the first $2,000 and the insurer would cover the remaining eligible amount, subject to policy terms.
Choosing a higher deductible can lower your monthly or annual premium. However, you need to make sure the deductible is an amount you can realistically afford after a loss. A high deductible may look good when you are shopping for a policy, but it can create financial stress when you need to file a claim.
Homeowners should think about their emergency savings, risk exposure, and ability to cover repairs quickly. If you live in an area where storms, theft, or other claims are more likely, a lower deductible may be worth the higher premium. If you have strong savings and a lower-risk property, a higher deductible may make sense.
Check the Financial Strength of the Insurance Company
Price and coverage are important, but so is the insurance company’s ability to pay claims. A policy is only useful if the insurer can respond when you need help. That is why homeowners should compare insurance company ratings, not just customer reviews.
Industry rating agencies evaluate insurers based on financial strength and claim-paying ability. Moody’s and A.M. Best are two examples of organizations that review insurance companies. Their ratings can help you understand whether an insurer is financially stable enough to handle claims.
Consumer reviews can provide insight into customer service, but they should not be the only source you use. Some reviews are based on individual experiences that may not represent the full company. Industry ratings, claims data, policy terms, and service quality should all be considered together.
If you are in Georgia, you may also review this resource for homeowner insurance options and companies in that market.
Location Matters When Buying Home Insurance
Location affects almost every part of homeownership, including the cost of insurance. A home in a high-risk location may cost more to insure even if the purchase price is lower. Insurance companies calculate premiums based partly on how likely the property is to experience a loss.
Insurers may consider location-based factors such as:
- Distance from a fire station
- Local crime rates
- Risk of wildfires
- Storm and hurricane exposure
- Flood zone status
- Earthquake risk
- Local building costs
- Age and condition of nearby infrastructure
- History of claims in the area
A house that is far from a fire station may have higher fire-related risk. A home in an area with higher theft or vandalism rates may cost more to insure. A property near the coast may face higher wind or hurricane exposure. A home near water may require separate flood insurance.
This is why two similar homes can have very different insurance premiums. The structure matters, but the surrounding risk environment matters too.
Understand What Your Home Insurance Policy Actually Covers
One of the most important steps in buying home insurance is understanding what the policy will and will not pay for. Homeowners often assume that a standard policy covers every type of disaster, but that is not always true.
For example, a homeowners policy may cover wind damage but exclude flood damage. After Hurricane Katrina, many homeowners discovered that damage from rising water was not covered by their standard policies, even if they had coverage for hurricane-related wind damage. This type of misunderstanding can create devastating financial consequences.
Before buying a policy, ask clear questions:
- Does the policy cover wind damage?
- Does the policy cover flood damage?
- Does the policy cover sewer backup?
- Does the policy cover mold?
- Does the policy cover earthquakes?
- Does the policy cover personal belongings away from home?
- Does the policy cover temporary housing after a covered loss?
- Are there separate deductibles for wind, hail, or hurricanes?
Many risks require separate coverage or endorsements. Flood insurance, earthquake insurance, sewer backup coverage, and high-value item riders may not be included in a standard policy. Reading the policy before a claim is much better than discovering exclusions after a disaster.
Calculate Replacement Cost vs. Actual Cash Value
Before you sign a policy, confirm whether your home and belongings are covered for replacement cost or actual cash value. This difference can have a major impact on how much money you receive after a claim.
Replacement cost coverage helps pay the cost to repair or rebuild your home using today’s labor and material prices, subject to policy limits. Actual cash value coverage subtracts depreciation, which means older items may be valued for much less than the cost to replace them.
For example, if your roof is damaged, replacement cost coverage may help pay for a new roof based on current costs. Actual cash value coverage may reduce the payout based on the roof’s age and condition. The same concept can apply to furniture, electronics, appliances, and other personal belongings.
Replacement-cost coverage usually costs more, but it can provide stronger protection after a major loss. Ask your agent for a detailed replacement-cost estimate and review it regularly. Building costs can rise over time, and major renovations can increase the amount of coverage you need.
If a premium increase creates short-term budget pressure, flexible financing options such as loans for bad credit online guaranteed approval may help some homeowners manage temporary costs without relying on high-interest credit cards.
Review Add-Ons and Riders for Specialized Coverage
A standard homeowners policy may not fully cover every item or risk. Many policies have limits for jewelry, collectibles, art, expensive electronics, home-office equipment, tools, firearms, or musical instruments. If you own valuable items, you may need to schedule them separately or add a rider.
Common home insurance endorsements may include:
- Jewelry and valuable items coverage
- Water backup coverage
- Identity theft protection
- Equipment breakdown coverage
- Ordinance or law coverage
- Home business coverage
- Service line coverage
- Extended replacement cost coverage
- Scheduled personal property coverage
An ordinance or law endorsement can be especially important for older homes. If your home is damaged and local building codes require upgrades during repairs, this coverage may help pay for the additional cost. Without it, you may need to pay code-related expenses yourself.
Some riders require appraisals, receipts, photos, or updated security measures. If you need to cover an appraisal or small coverage-related expense quickly, a $500 cash advance no credit check may help keep the process moving without delaying your policy update.
Use Discounts and Bundling to Lower Home Insurance Premiums
Home insurance can be expensive, but many insurers offer discounts that can reduce your premium without reducing important coverage. The key is to ask which discounts are available and whether your home qualifies.
Common homeowners insurance discounts may include:
- Bundling home and auto insurance
- Installing monitored security systems
- Adding smoke detectors or fire alarms
- Installing smart water leak detectors
- Using impact-resistant roofing materials
- Upgrading electrical, plumbing, or HVAC systems
- Having a claims-free history
- Choosing paperless billing or automatic payments
- Being a new homebuyer
- Living in a gated community
Bundling home and auto insurance with the same carrier can often reduce costs and simplify policy management. Safety upgrades can also lower risk, which may result in lower premiums.
If you need to finance security improvements up front, a 1000 dollar loan may help install protective devices now while you work toward potential savings over the policy term.
Understand How Credit Can Affect Home Insurance Premiums
In many states, insurance companies may use credit-based insurance scores when setting home insurance premiums. This is not the same as a standard credit score, but it is often based on similar financial behavior. A stronger credit profile may help some homeowners qualify for lower premiums, while a weaker score may increase costs.
Insurers may view credit behavior as one factor in predicting claim risk. This practice is regulated and may not be allowed everywhere, so rules depend on your location.
To improve your financial profile before renewal, consider steps such as:
- Paying bills on time
- Reducing credit card balances
- Keeping credit utilization low
- Checking credit reports for errors
- Disputing inaccurate information
- Avoiding unnecessary new credit applications
If you are trying to consolidate expensive debt before your insurance renewal, online loans for bad credit may be one option to review as part of a broader plan to improve cash flow and rebuild credit health over time.
Prepare for the Claims Process Before Disaster Strikes
The best time to prepare for a home insurance claim is before damage happens. A well-documented claim is often easier to file and may be processed more smoothly. Homeowners should keep records, photos, receipts, and policy information organized in advance.
To prepare for the claims process:
- Create a room-by-room video inventory of your home
- Take photos of valuable items
- Store receipts for major purchases
- Keep copies of renovation invoices
- Back up documents in cloud storage
- Save your policy declarations page
- Keep emergency contact numbers available
- Update your inventory after major purchases
A home inventory can help prove what you owned and what was damaged or lost. This is especially important after fire, theft, or severe storm damage when it may be difficult to remember every item.
Temporary lodging, travel, and emergency supplies can become expensive after a disaster. If cash reserves are strained while waiting for reimbursement, short-term options such as i need cash today may help cover urgent costs during the claims process.
Bridge Deductible Gaps With a Short-Term Financial Plan
Choosing a higher deductible can reduce your premium, but it also creates a responsibility to pay more out of pocket when a claim happens. Homeowners should not choose a deductible based only on monthly savings. They should also have a plan for paying that deductible quickly if repairs are needed.
A good rule is to keep at least the full deductible amount in an emergency fund. If your policy has separate deductibles for wind, hail, hurricane, or other risks, make sure you understand how much you may owe after different types of claims.
If a major claim happens before your emergency fund is fully built, a 1500 dollar loan may provide a short-term bridge so repairs can begin quickly and further damage can be avoided.
Common Home Insurance Mistakes to Avoid
Many homeowners make insurance decisions quickly, especially when buying a home under time pressure. However, rushing can lead to coverage gaps or unnecessary costs. Avoiding common mistakes can help you choose better protection.
Common home insurance mistakes include:
- Choosing the cheapest policy without checking coverage
- Insuring the home for market value instead of rebuild cost
- Ignoring flood or earthquake risk
- Setting a deductible too high to afford
- Failing to update coverage after renovations
- Not scheduling valuable items separately
- Assuming personal belongings are fully covered
- Not reviewing policy exclusions
- Forgetting to compare quotes at renewal
- Not documenting belongings before a claim
Your home insurance needs can change over time. Renovations, rising construction costs, new belongings, home-based businesses, new security systems, and changes in local risk can all affect coverage. Reviewing your policy once a year can help keep protection aligned with your current situation.
How Often Should You Review Your Home Insurance Policy?
Homeowners should review their insurance policy at least once a year, usually before renewal. You should also review coverage after any major change to your home or finances.
Review your policy when you:
- Remodel or add square footage
- Replace the roof
- Install a pool or detached structure
- Buy expensive jewelry, electronics, or collectibles
- Start a home-based business
- Rent part of the home
- Pay off your mortgage
- Change security systems
- Move to a higher-risk area
- Notice major premium increases
An annual review can help you find discounts, update coverage limits, adjust deductibles, and make sure you are not underinsured.
Final Thoughts on How to Buy Home Insurance
Home insurance is essential when you own a major asset like a house. Real estate is valuable, but it is also exposed to environmental, physical, legal, and financial risks. Fire, storms, theft, liability claims, and unexpected damage can create costs that are difficult to manage without insurance.
To buy home insurance wisely, compare multiple quotes, understand your location-based risks, review deductibles, check insurer ratings, and read the policy carefully. Make sure you know what is covered, what is excluded, and whether your home is insured for replacement cost or actual cash value.
The right homeowners insurance policy should protect more than the building. It should support your financial security, help you recover after covered losses, and give you confidence that your largest investment is better protected.


 Get Our RSS
 Follow us on Twitter
 Like us on Facebook
 Circle us on Google+
 EasyFinance Blog
 Twitter
 Facebook
 Google+
 LinkedIn
 Email Subscriptions
Leave a Reply: