

Can I Afford a $500 Loan? Debt-to-Income and Budget Template in 2026
Borrowing $500 may sound manageable, but for many households it can mean the difference between staying current on rent, keeping utilities on, covering a car repair, buying groceries, or paying an urgent medical bill. Before taking out any loan, it is important to check whether the repayment will realistically fit your budget.
Looking at your debt-to-income ratio, fixed bills, flexible expenses, and available cash flow can help you avoid borrowing more than you can comfortably repay. EasyFinance.com, a BBB-accredited business, helps borrowers compare trusted online lenders offering fast and transparent loan options up to $2,000, while making it easier to understand affordability before applying.
When borrowers search i need $500 dollars now no credit check, the urgency is real. But fast access to money only helps if the repayment does not create a second financial problem next month.
Can You Afford a $500 Loan?
You may be able to afford a $500 loan if the repayment fits comfortably after rent, utilities, food, transportation, insurance, childcare, medical needs, and existing debt payments. The key question is not only whether a lender will approve you. The better question is whether the loan payment will leave enough money for essentials after it comes due.
A $500 loan may be affordable when:
- You know the exact total repayment amount before accepting
- The due date lines up with your paycheck or benefit deposit
- You can repay without missing rent, utilities, food, transportation, or other essentials
- You do not need another loan to repay this one
- You have compared payday-style and installment-style repayment options
A loan may be risky if the payment would use most of your next paycheck or leave you short on basic expenses.
What Debt-to-Income Ratio Means
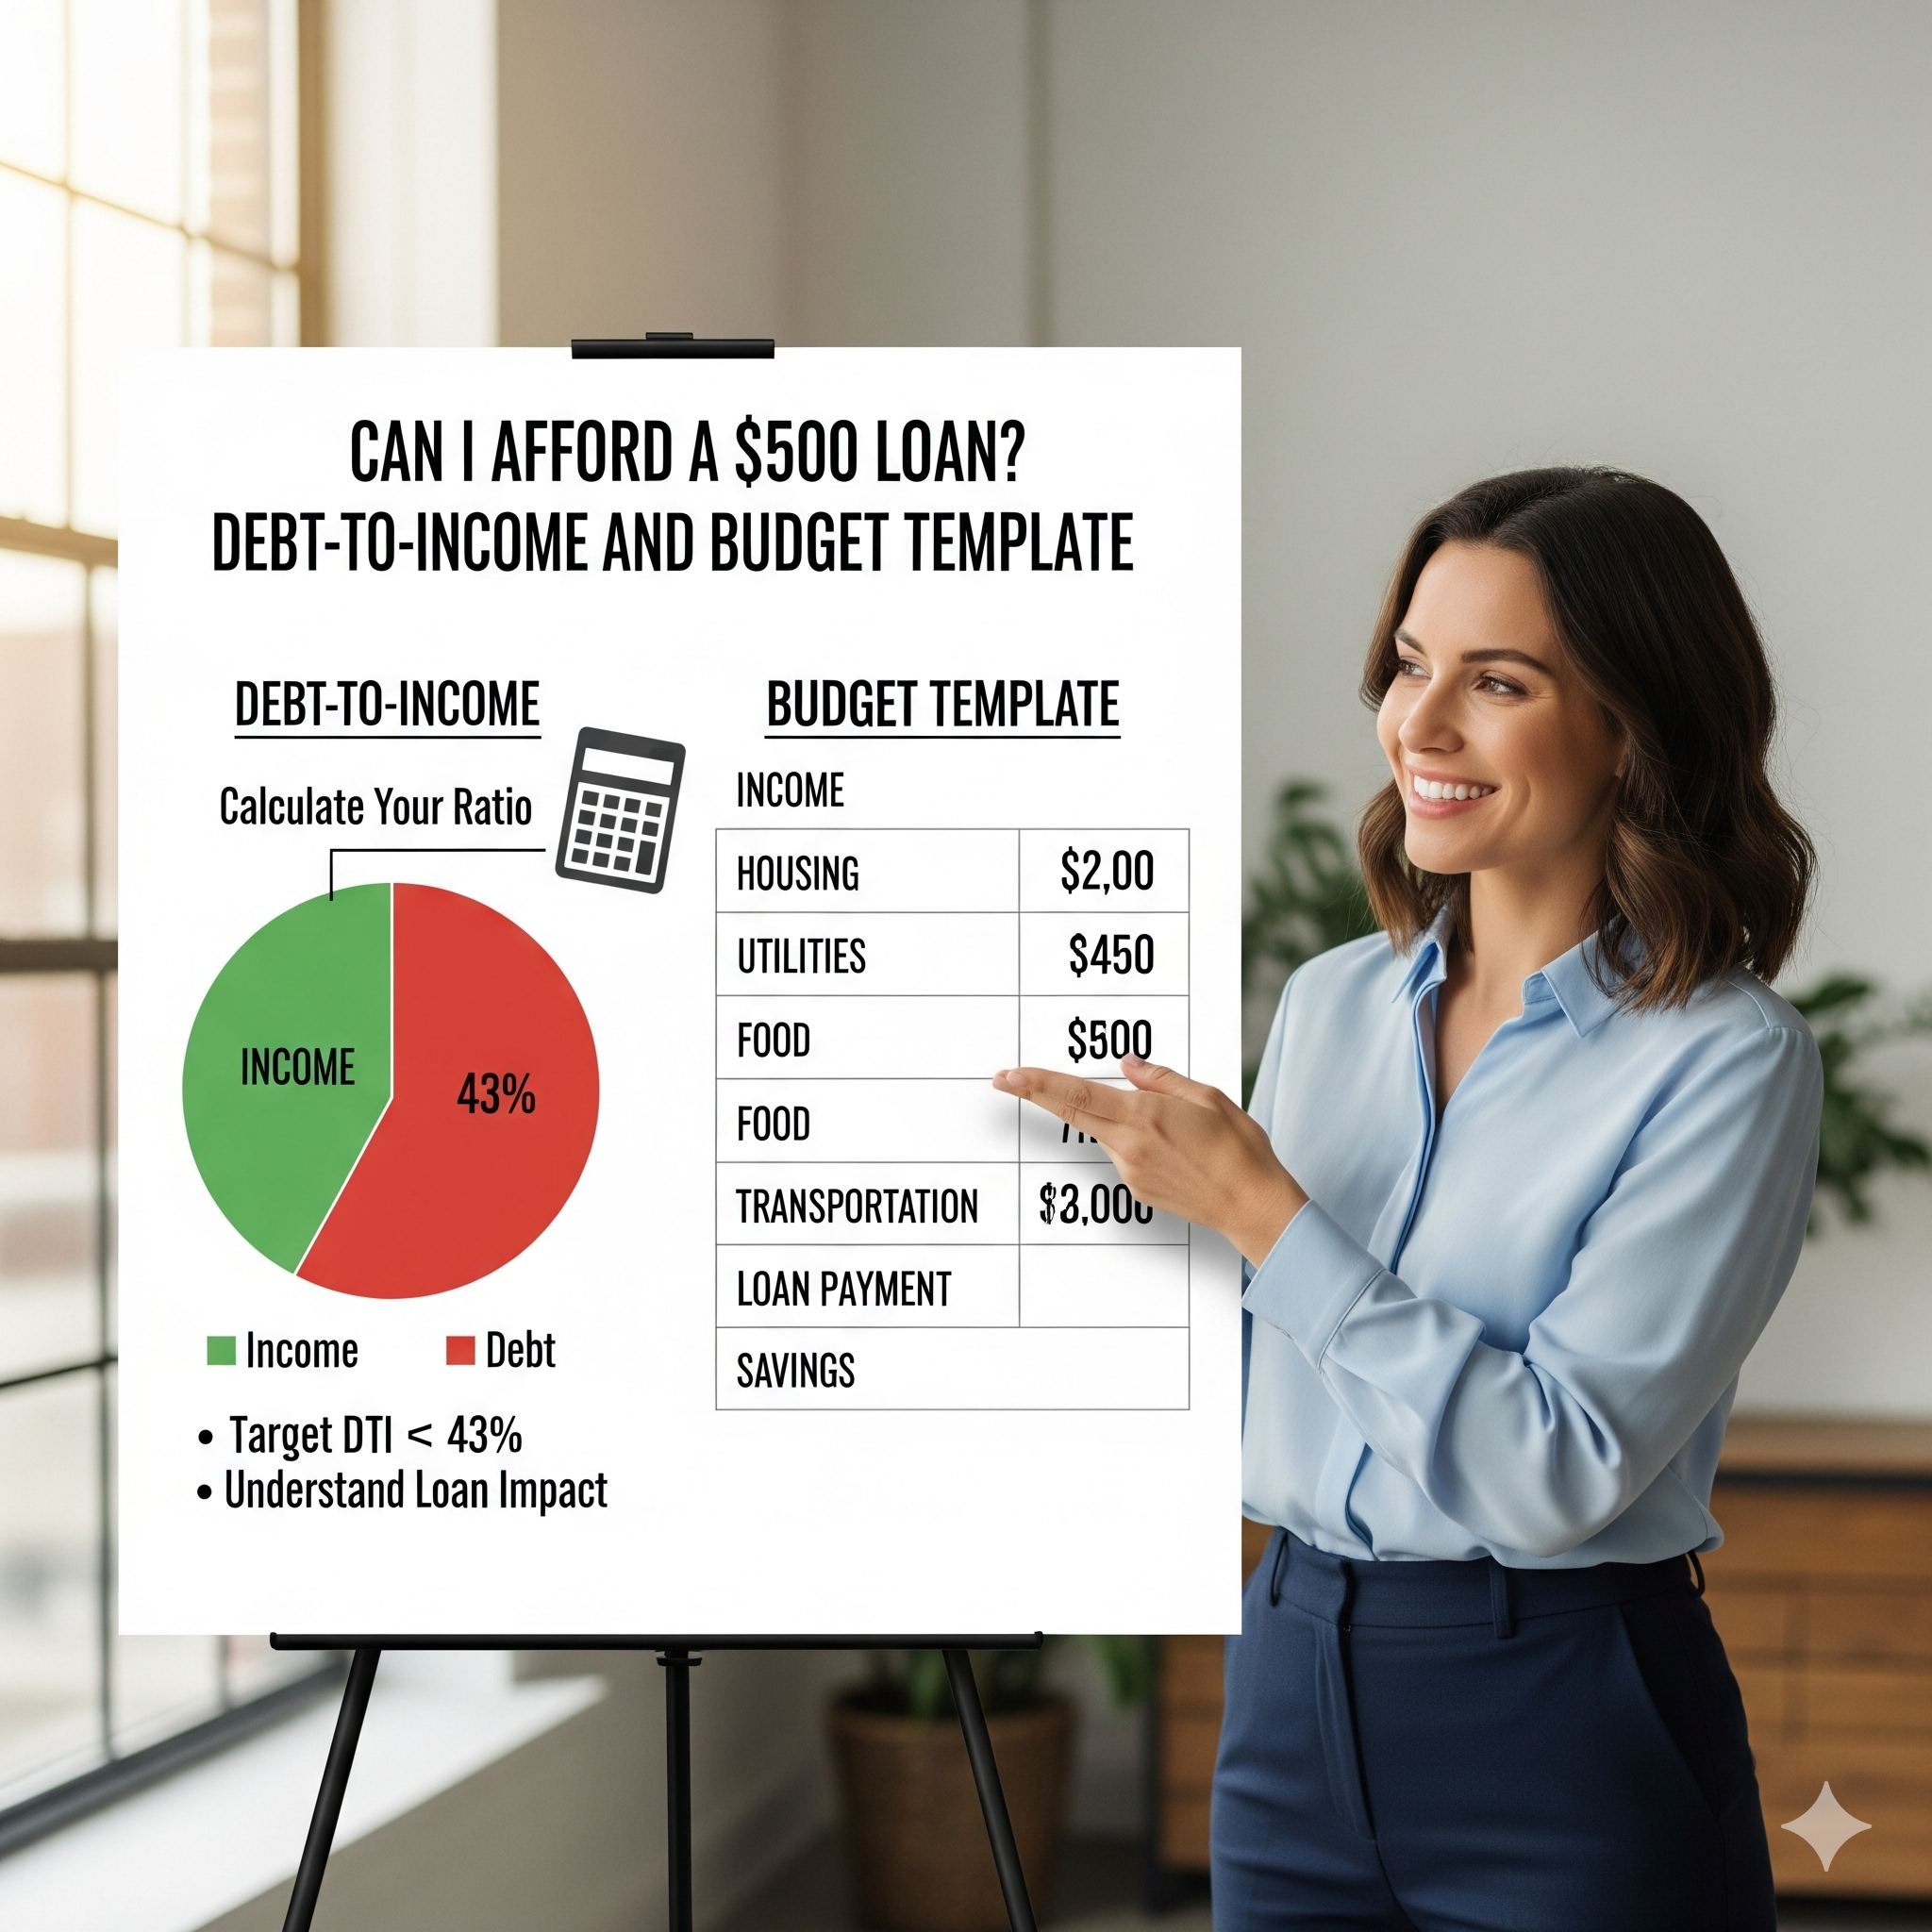
Your debt-to-income ratio, often called DTI, measures how much of your gross monthly income already goes toward debt obligations. It is one of the simplest ways to judge whether adding a new loan payment makes sense.
A simple DTI formula looks like this:
Monthly debt payments ÷ gross monthly income = DTI ratio
Example:
- Gross monthly income: $2,500
- Existing monthly debt payments: $1,000
- DTI: 40%
If you add a new loan payment on top of that, your monthly financial pressure goes higher. That does not always mean you cannot borrow, but it does mean you should review your budget carefully before accepting the loan.
What DTI Ratio Is Usually Safer?
There is no single DTI number that guarantees approval or safety. Many lenders use their own standards, and small-dollar lenders may approve borrowers with higher ratios if income is steady and recent deposits support repayment. Still, lower DTI usually gives borrowers more room to handle unexpected costs.
As a general affordability guide, many financial resources use 36% or lower as a common debt-to-income benchmark for all debts. Some lenders may allow higher ratios, but a higher DTI can mean less room for another payment.
| DTI Range | What It May Mean | What to Consider Before Borrowing |
|---|---|---|
| Below 20% | Lower debt pressure | You may have more room, but still check total repayment and due date |
| 20% to 36% | Moderate debt pressure | A $500 loan may be manageable if the payment fits after essentials |
| 37% to 43% | Higher debt pressure | Be cautious, especially with one-payment payday loans |
| Above 43% | Heavy debt pressure | Consider smaller amounts, installment options, or non-loan alternatives first |
If your DTI is already high, a one-payment product such as a 500 payday loan may be harder to manage than an installment option that spreads payments over time.
How to Test Whether a $500 Loan Fits Your Budget
The easiest way to check affordability is to build a simple monthly budget. Start with take-home income, then subtract fixed expenses, flexible essentials, current debt payments, and irregular costs. What remains is the amount available for emergency repayment, savings, or unexpected bills.
A basic budget review should include:
- Take-home monthly income
- Rent or mortgage
- Utilities
- Groceries
- Transportation
- Insurance
- Minimum debt payments
- Childcare or medical essentials
- Phone, internet, and recurring subscriptions
- Other recurring expenses
If there is not enough room after these categories, the loan may be harder to afford than it first appears.
Simple Example Budget for a $500 Loan
Here is a simple example:
- Monthly take-home income: $2,500
- Fixed expenses: $1,200
- Flexible essentials and living costs: $600
- Existing debt payments: $300
- Remaining amount: $400
At first glance, this borrower may seem close to being able to handle a $500 loan. But if the loan requires $575 to $600 in repayment within two weeks, the payment may not fit. If the loan is split into smaller installments, it may be easier to manage, but the borrower still needs to compare total cost.
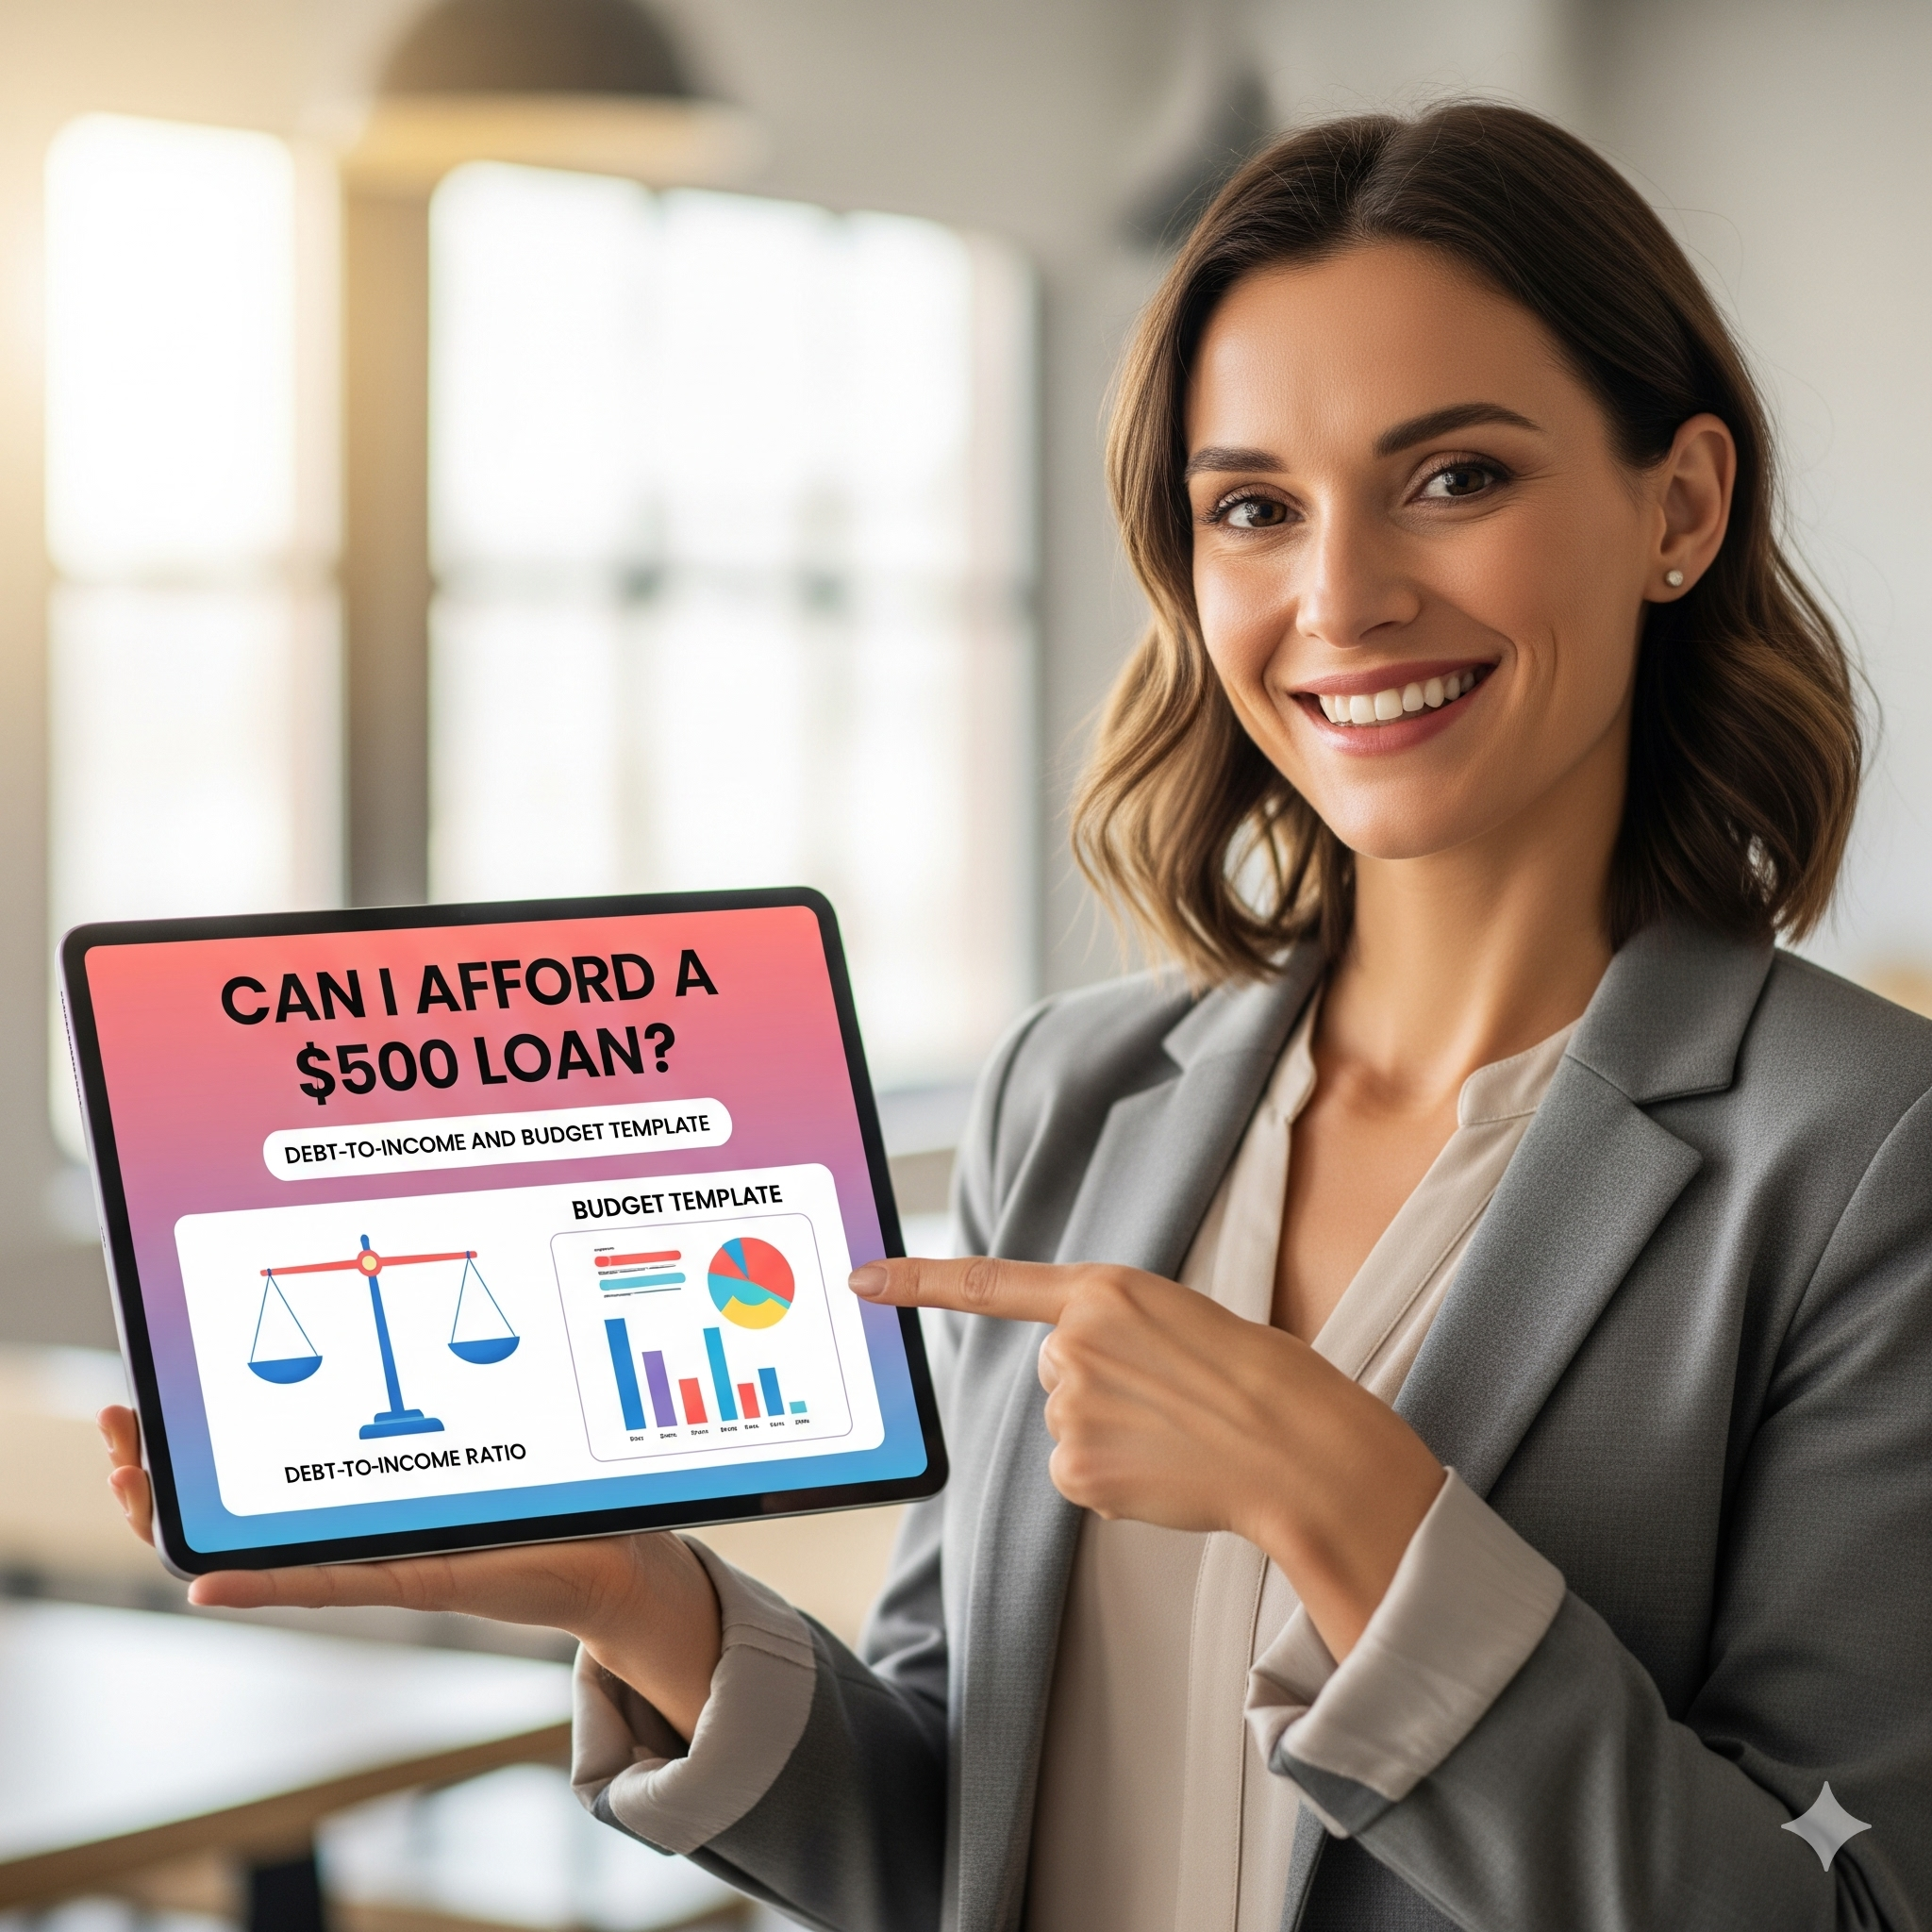
Sample Budget Template for a $500 Loan
Use this simple template before borrowing. Replace the example numbers with your own.
| Category | Example Amount | Your Amount |
|---|---|---|
| Monthly Take-Home Income | $2,500 | $_____ |
| Rent/Mortgage | $1,000 | $_____ |
| Utilities | $200 | $_____ |
| Groceries | $400 | $_____ |
| Transportation | $250 | $_____ |
| Insurance | $150 | $_____ |
| Existing Debt Payments | $250 | $_____ |
| Other Expenses | $250 | $_____ |
| Available for Loan Repayment | $0 to $300 | $_____ |
In this example, repaying a full $500 loan plus fees in one short repayment window may be difficult. An installment structure could be more manageable than a lump-sum payday payoff, but only if the scheduled payments fit the borrower’s actual budget.
Why the Loan Structure Matters
Two borrowers can have the same income and the same $500 emergency, but the right loan type may still be different. A payday-style loan often requires one large repayment quickly. An installment loan may spread the cost across multiple payments, which can reduce immediate pressure.
This is why borrowers comparing $500 payday loans online same day should not focus only on funding speed. They should also check whether the full repayment fits realistically into the next pay cycle.
| Loan Structure | How It Works | Affordability Question |
|---|---|---|
| One-payment payday loan | Repay the loan and fees in one lump sum | Can your next paycheck cover the full amount plus essentials? |
| Installment loan | Repay through scheduled payments over time | Can each payment fit without creating a monthly shortage? |
| Smaller loan amount | Borrow less than $500 if that solves the emergency | Would a smaller loan reduce repayment pressure? |
| Larger structured loan | Borrow more only if the emergency requires it | Does the larger payment schedule still fit your budget? |
Typical Costs of a $500 Loan
Costs vary by lender and state, but short-term payday-style products often charge fees of $15 to $20 per $100 borrowed. That means a $500 loan may cost $75 to $100 in fees if repaid quickly. If the loan is renewed, extended, or replaced with another one, the cost can rise fast.
Installment loans may spread cost over time, but they should still be evaluated by looking at:
- Total amount repaid
- APR or finance charges
- Payment schedule
- Late fees or extension costs
- Whether early payoff is allowed
- Whether repayment is automatic
Borrowers comparing $255 payday loans online same day or other small-dollar products should use the same logic. The smaller amount may feel safer, but the structure still matters.
When a $500 Loan May Be Hard to Afford
A $500 loan may be harder to manage when:
- Your DTI is already high
- You are behind on rent, utilities, or other essentials
- You would need another loan to repay the first one
- Your income changes from month to month
- You do not have enough room in the budget after fixed costs
- The loan requires one full repayment before your next stable income deposit
- The lender does not clearly disclose total repayment cost
If any of those are true, borrowing may still be possible, but the safer option is usually the one with lower immediate repayment pressure.
When a Different Loan Amount May Make More Sense
Sometimes $500 is too much, and sometimes it is not enough. In California and some other regulated markets, borrowers may only be able to access products such as $255 payday loans online same day California. In other cases, the emergency may be larger, and a structured 1000 dollar loan with installments may work better than taking multiple smaller short-term loans.
Borrowers searching i need 1000 dollars now are often dealing with a larger gap that a single short-term $500 loan will not solve completely.
The safest amount is usually the smallest amount that fully solves the emergency and can be repaid without damaging the rest of your budget.
No-Credit-Check and Income-Based Approval Options
Some borrowers with limited credit history or recent financial setbacks compare loans with no credit check. These lenders may focus more on income and deposit history than on a traditional credit score. That can improve access, but it does not remove the need to check affordability first.
“No credit check” does not mean “no review.” A lender may still verify identity, income, bank activity, state eligibility, and repayment ability before approving a loan.
If you are in an urgent situation and searching need cash now, the right question is not just whether you can get approved. It is whether the repayment will still leave enough money for essentials after the loan is due.
How to Borrow More Safely
Before taking a $500 loan, ask:
- Can I repay this without missing rent, food, utilities, or transportation?
- Will I still have enough money after the repayment date?
- Is the due date aligned with my pay cycle?
- Would installments be safer than one lump-sum payment?
- Am I borrowing only what I truly need?
- What happens if I cannot repay on time?
- Is there a cheaper alternative, such as a payment plan, employer advance, local assistance program, or credit union option?
Borrowing safely is less about the approval itself and more about making sure the loan solves today’s problem without making next month harder.
Common Budget Mistakes Before Taking a $500 Loan
Many borrowers underestimate repayment pressure because they focus on the loan amount instead of the total repayment amount. Avoid these common mistakes:
- Counting gross income instead of take-home income: Your paycheck after taxes and deductions is what matters for repayment.
- Ignoring irregular expenses: Car insurance, school costs, medical bills, and repairs can disrupt a tight budget.
- Assuming approval means affordability: A lender may approve a loan that still strains your household budget.
- Forgetting fees: A $500 loan may require $575 to $600 or more in repayment depending on the lender.
- Using another loan as the repayment plan: This can create a cycle of debt.
- Not comparing loan structures: Installments may be safer than one lump-sum repayment for some borrowers.
Why Borrowers Use EasyFinance.com
EasyFinance.com helps borrowers compare lenders more carefully so they can choose a loan that matches both the emergency and the budget.
- BBB-accredited business focused on transparency and borrower trust
- Loan options up to $2,000 from online lenders
- Fast comparison of short-term and installment products
- Options for borrowers with limited credit or nontraditional income
- Clearer view of repayment structure and affordability before accepting an offer
- Support for comparing approval speed, total cost, and repayment pressure
Loan Affordability in 2026
In 2026, fast online approvals are easier to find, but affordability remains the most important part of responsible borrowing. With household budgets under pressure, more borrowers are using budgeting tools and debt-to-income checks before applying.
That shift matters because the best loan is not just the one you can get today. It is the one you can repay without losing financial stability next month.
Key Insights
- Debt-to-income ratio is one of the best starting points for deciding whether a $500 loan is affordable.
- A simple budget template can show whether repayment fits after rent, food, utilities, transportation, and other essentials.
- Payday-style loans may be fast, but one-payment repayment can create pressure if your budget is already tight.
- Installment structures may be easier to manage when you need more time to repay.
- State rules can affect loan size, especially in capped markets like California.
- No-credit-check lenders may expand access, but they do not remove the need to check affordability carefully.
- The best loan is the one that solves the emergency without pushing your budget into a new crisis.
- Borrowers should compare total repayment, payment timing, fees, APR, and monthly cash flow before accepting any offer.
FAQ
- What DTI ratio is usually safer for a $500 loan?
- Many financial resources use 36% or lower as a common debt-to-income benchmark, but small-dollar lenders may use different standards. Even if approval is possible at a higher DTI, lower DTI usually makes repayment safer.
- How do I calculate my debt-to-income ratio?
- Add your monthly debt payments, divide that amount by your gross monthly income, and multiply by 100. For example, $1,000 in monthly debt payments divided by $2,500 in gross income equals a 40% DTI.
- Can I get a $500 loan without a credit check?
- Some lenders offer $500 cash advance no credit check products that rely more on income, deposits, and bank activity than on traditional credit history.
- What if I only need a smaller amount?
- In some states, products such as $255 payday loans online are more common because of state loan caps. Borrowing less may also reduce repayment pressure if the smaller amount solves the emergency.
- Can I get a larger amount if $500 is not enough?
- Sometimes yes. Borrowers may compare a i need $1,000 dollars now no credit check option when the emergency is larger and an installment structure may make repayment easier.
- How fast can I get the funds?
- Some lenders may offer same-day approvals or next-business-day funding, depending on the lender, time of application, verification, bank processing, and funding method.
- Do lenders actually check my budget?
- Some lenders review income, deposits, and debt obligations, but creating your own budget first is one of the best ways to avoid overborrowing.
- Is a payday loan or installment loan easier to afford?
- It depends on your budget. A payday loan may be faster but often requires one full repayment. An installment loan may spread payments over time, which can be easier to manage if the total cost is reasonable.
- What is the biggest warning sign that I cannot afford a $500 loan?
- A major warning sign is needing another loan to repay the first one. Another is being unable to repay while still covering rent, utilities, food, transportation, and other essentials.
- How does EasyFinance.com help?
- EasyFinance.com helps borrowers compare transparent offers from lenders so they can find a loan that better fits both their emergency and their budget.
- Is EasyFinance.com a lender?
- No. EasyFinance.com connects applicants with lenders and lending partners. It is not itself a lender, and loan approval, fees, APR, funding speed, and repayment terms depend on the lender.
This article is for informational purposes only and does not constitute financial advice. EasyFinance.com connects applicants with lenders and is not itself a lender. Loan availability, approval, funding speed, fees, APR, repayment terms, and loan amounts vary by lender, borrower eligibility, income, credit profile, and state law. Always review the full loan agreement before accepting any offer.
$500 Loans Related Articles
- $500 Loans: How to Get a $500 Loan Online Today
- $500 Installment Loans Online
- $500 Loans for Bad Credit
- $500 Loan No Hard Credit Check Alternatives
- Compare $300 vs $500 vs $700 Loans: Costs, Speed, and Approval Odds
- Same Day $500 Loans: Cutoff Times, Direct Deposit, and Cards
- Weekend and Holiday $500 Loans
- Instant $500 Loans to Prepaid and Debit Cards
- $500 Loans Without a Bank Account: Cash Pickup and Card Options
- $500 Loan for Emergency Expenses
- $500 Loan for Rent or Utilities
- $500 Loan for Car Repairs
- $500 Loan for Medical Bills
- $500 Loans for Gig Workers and 1099 Earners
- $500 Loans While Unemployed
- $500 Loans on SSI and SSDI
- $500 Loans for Students
- $500 Loans for Single Parents
- $500 Loans for Military and Veterans
- Approval Odds for a $500 Loan by Credit Score Band
- Documents You Need for a $500 Loan
- $500 Loans Without a Cosigner: Realistic Paths
- Soft Pull vs Hard Pull for $500 Loans
- True Cost of a $500 Loan: APR vs Fees, Example Repayments
- $500 Payday vs $500 Installment vs Credit Builder Loan
- Can I Afford a $500 Loan? Debt-to-Income and Budget Template
- Early Payoff and Extensions on a $500 Loan
- Best $500 Loan Apps for Fast Funding

 EasyFinance Blog
 Twitter
 Facebook
 Google+
 LinkedIn
 Email Subscriptions
