

$500 Loan vs $1000 Loan: Which Is Better for Emergencies in 2026?
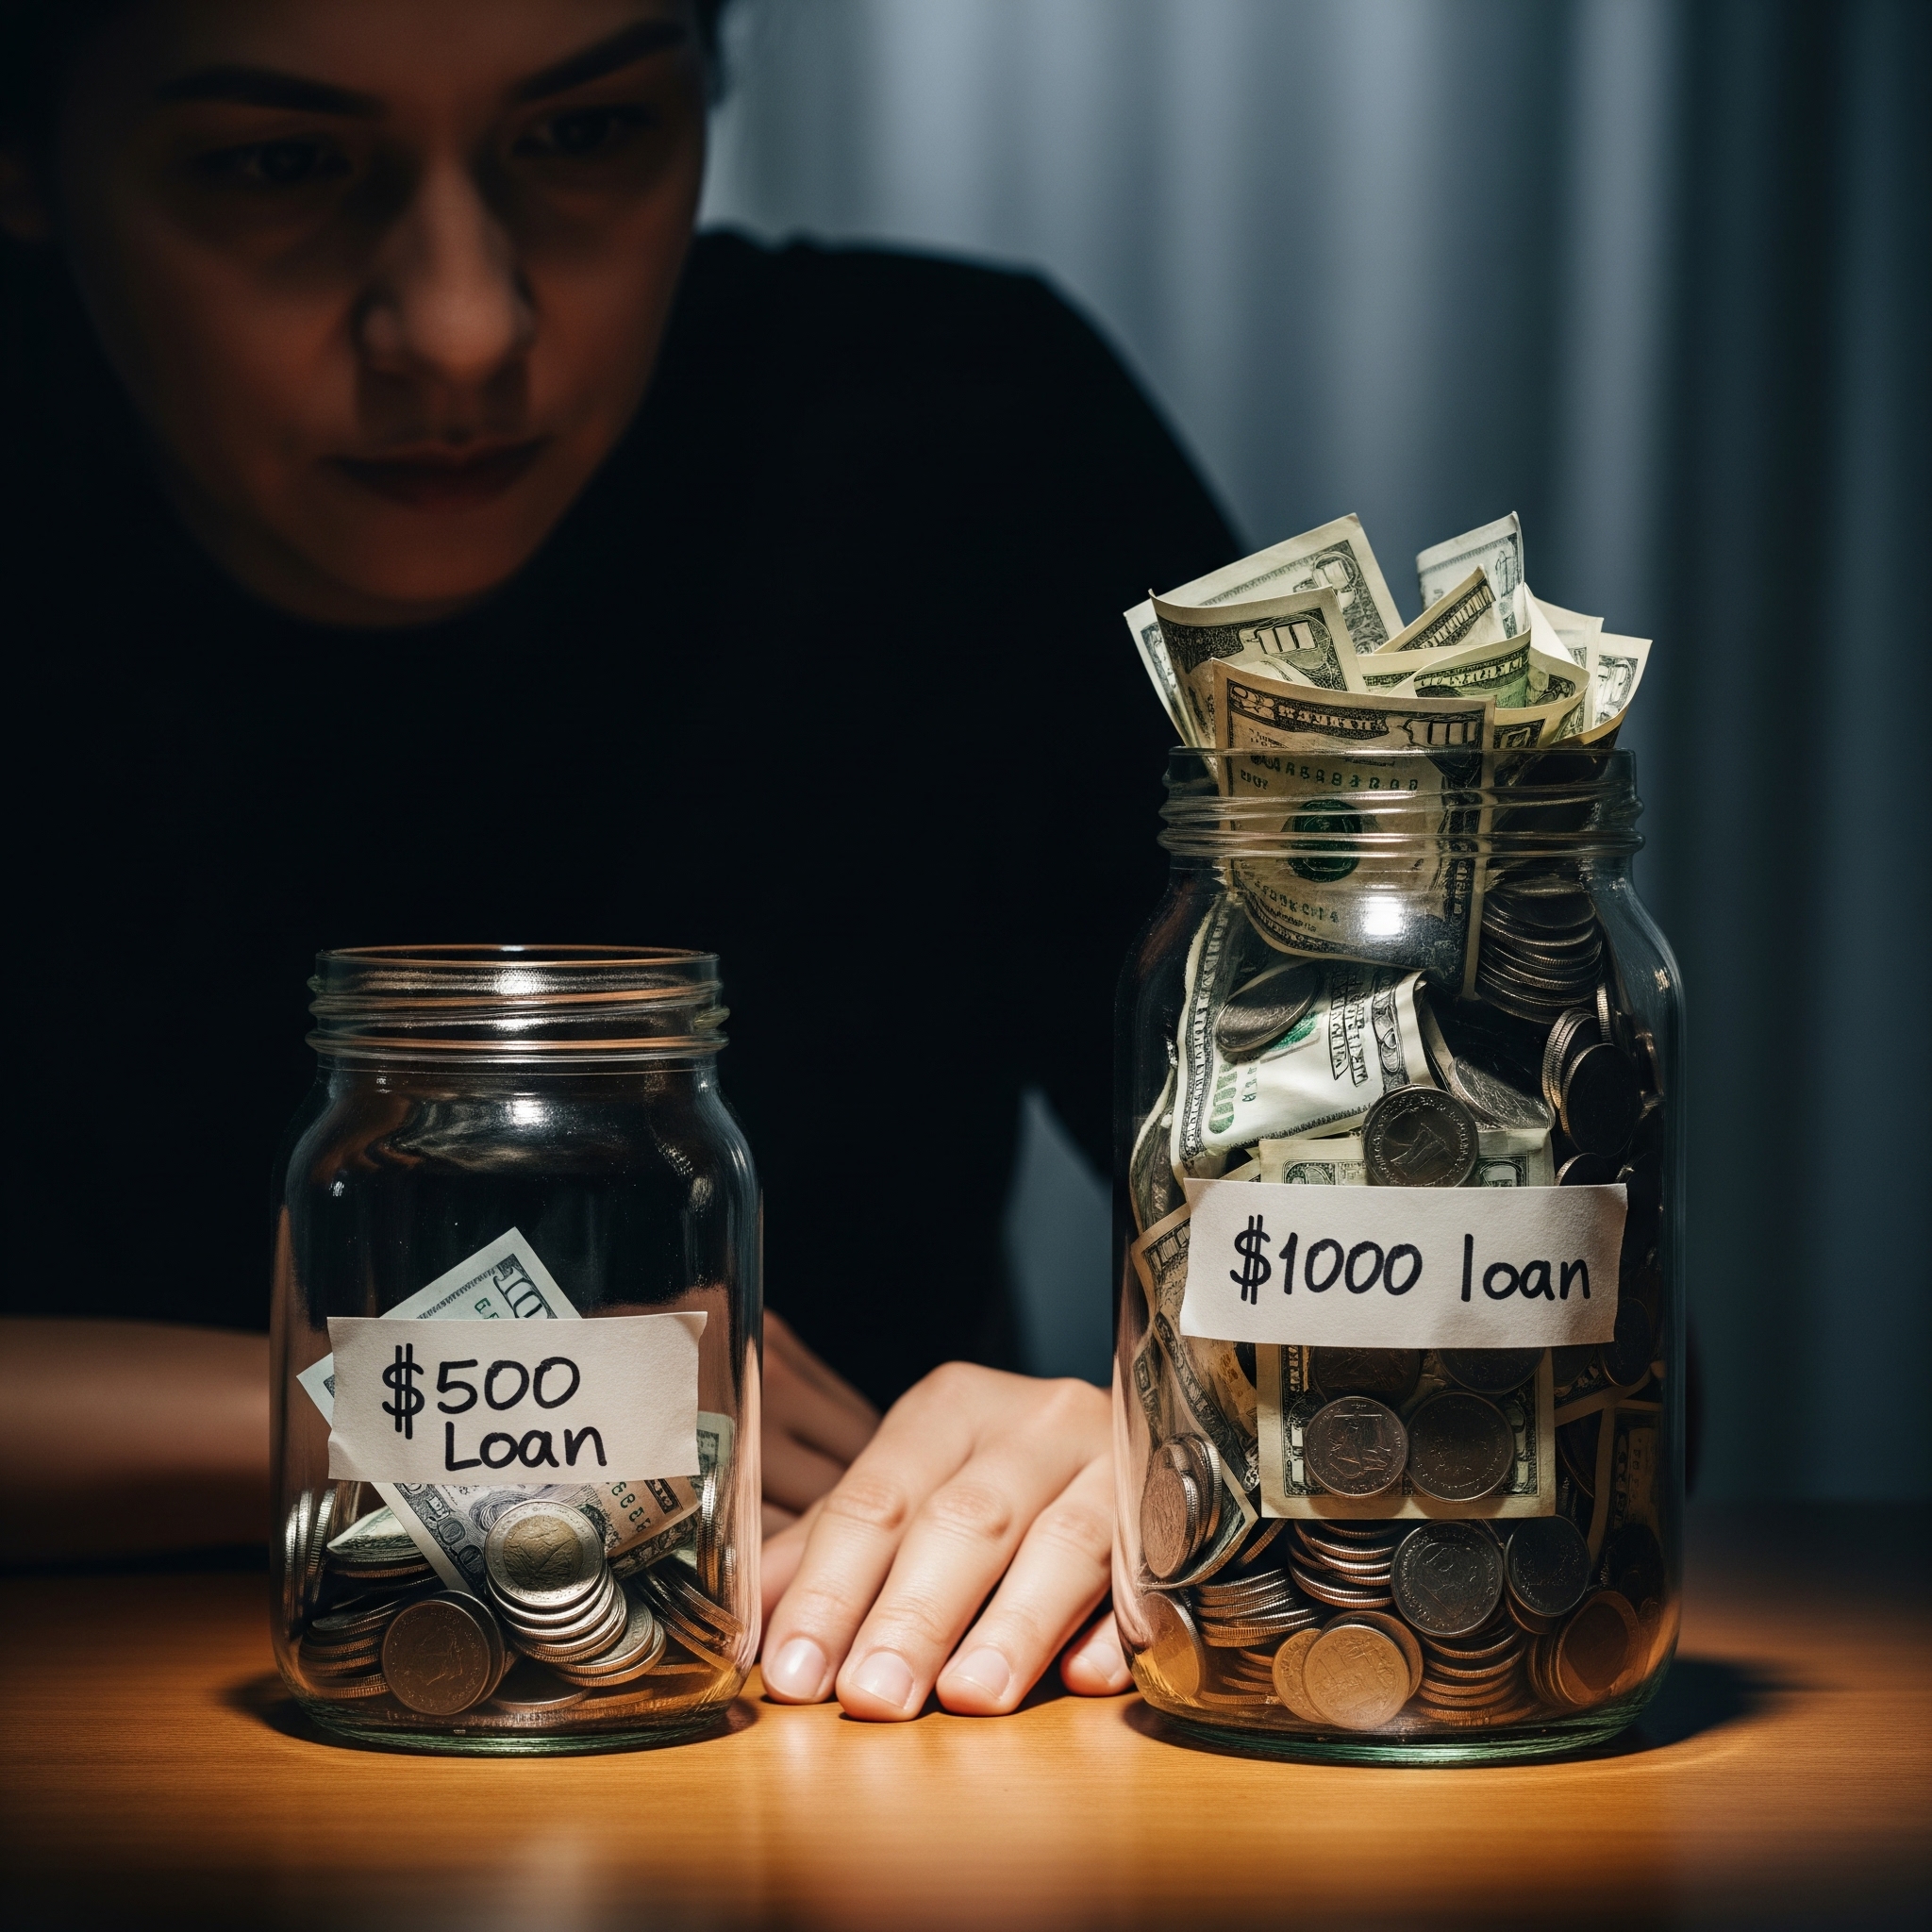
When a financial emergency hits, one of the first decisions borrowers face is how much to request. A $500 loan may be enough for a smaller urgent expense, while a $1,000 loan may make more sense when several bills or a larger emergency need to be covered at once. The right choice depends on the size of the expense, the repayment schedule, the total cost, and your ability to repay without creating another cash shortage.
Updated May 2026: EasyFinance.com is a BBB-accredited marketplace that helps borrowers compare online emergency loan options from participating lenders.
EasyFinance.com helps borrowers compare online loan options from participating lenders, including $500 cash advances, $1,000 emergency loans, payday-style loans, installment-style loans, small personal loans, bad-credit loan options, and no-credit-check-style products. Approval amounts, funding speed, APR, fees, repayment terms, and final loan availability depend on lender review, verification, state availability, bank processing, income, and ability to repay.
This guide explains when a $500 loan may be better, when a $1,000 loan may be more practical, how costs and repayment differ, what lenders may review, and how to avoid borrowing too little or too much.
$500 Loan vs. $1,000 Loan: Quick Answer
- A $500 loan may work better for smaller emergencies such as groceries, prescriptions, utility bills, gas, or minor repairs.
- A $1,000 loan may be more useful for larger expenses such as rent gaps, major car repairs, medical bills, or multiple urgent bills.
- Borrowing less can reduce total repayment and repayment pressure.
- Borrowing more may help avoid taking multiple smaller loans, but it also creates a larger repayment obligation.
- Same-day or next-business-day funding may be possible with some lenders, but approval and funding speed are not guaranteed.
- The safest choice is the smallest loan amount that fully solves the urgent problem and fits your repayment ability.
When a $500 Loan May Be the Better Choice
A $500 loan may be a better fit when the emergency is limited, specific, and short term. Because the loan amount is smaller, the repayment obligation may be easier to manage than a larger loan, assuming the fees and payment schedule are affordable.
Borrowers often compare $500 cash advance no credit check options for smaller urgent needs such as:
- groceries, gas, or prescriptions
- a smaller utility bill
- a short cash gap before payday
- a minor car repair
- a medical copay or dental bill
- an insurance payment
- an emergency household expense
A $500 loan may be risky if the payment would leave no room for essentials or if you expect to need another loan immediately after repayment.
When a $1,000 Loan May Make More Sense
A $1,000 loan may be more practical when the emergency is larger than $500 or when several urgent expenses need to be handled at once. For example, a larger car repair, rent shortage, medical bill, emergency travel cost, or combined utility and household expense may require more than a smaller cash advance.
Borrowers comparing a $1,000 loan should focus on whether the larger payment schedule fits their income. A larger loan can help avoid multiple smaller loans, but it can also increase total repayment and create more pressure if the terms are not manageable.
Comparing $500 and $1,000 Loans
| Factor | $500 Loan | $1,000 Loan |
|---|---|---|
| Best for | Smaller urgent expenses or short cash gaps. | Larger emergencies or several bills at once. |
| Repayment pressure | Usually lower because the amount borrowed is smaller. | Usually higher because the repayment obligation is larger. |
| Total cost | May cost less in total dollars if fees and terms are reasonable. | May cost more in total dollars because the borrowed amount is larger. |
| Risk of borrowing too little | May not fully solve the emergency. | Less likely to leave part of the emergency uncovered. |
| Risk of borrowing too much | Lower if $500 fully solves the problem. | Higher if you only needed a smaller amount. |
| Best decision rule | Use when $500 covers the full urgent need. | Use only when the larger amount is truly needed and affordable. |
Comparing Costs: APR, Fees, and Total Repayment
A $500 loan may have a lower total repayment amount because you are borrowing less. However, the APR, finance charges, and fee structure can vary by lender and loan type. A $1,000 loan may offer a different repayment structure, but it still needs to be evaluated based on total repayment and payment timing.
Before choosing either amount, compare:
| Cost Factor | Why It Matters | Question to Ask |
|---|---|---|
| APR | Shows the annualized cost of borrowing, including interest and certain fees. | “What APR applies to this offer?” |
| Total repayment | Shows the full dollar amount you will repay from start to finish. | “How much will I repay in total?” |
| Finance or origination fees | Fees can increase the cost of both small and larger loans. | “Are fees deducted upfront or included in repayment?” |
| Payment dates | Due dates should match your income schedule. | “Will payment fall after my paycheck or deposit clears?” |
| Repayment structure | Some loans use one payment, while others use scheduled installments. | “Is this repaid in one payment or multiple payments?” |
| Late or returned-payment fees | Missed or failed payments can increase cost quickly. | “What happens if I pay late or payment fails?” |
The best loan amount is not always the largest amount available. It is the amount that solves the emergency with the lowest practical repayment pressure.
Approval Speed and Funding Timing
Both $500 and $1,000 loans may be reviewed quickly by some online lenders. Some approved borrowers may receive funds the same business day or by the next business day, depending on lender timing and bank processing.
However, approval and same-day funding are not guaranteed. Timing depends on lender review, identity and income verification, application time, cutoff times, signed acceptance, funding method, and your bank’s deposit schedule.
Borrowers searching for $500 payday loans online same day no credit check or I need $1,000 dollars now no credit check should still review APR, fees, payment dates, and total repayment before accepting any offer.
How to Decide Which Loan Amount Fits Your Situation
Before choosing between $500 and $1,000, write down the exact emergency expense and compare it with the full repayment obligation. Borrowing too little may leave you short. Borrowing too much may increase cost unnecessarily.
| Situation | Better Starting Point | Why |
|---|---|---|
| You need $200-$400 | $255-$500 loan | A smaller loan may reduce repayment pressure. |
| You need about $500 | $500 loan | Borrowing close to the exact need can limit total repayment. |
| You need $700-$1,000 | $1,000 loan | A larger loan may cover the full emergency without a second application. |
| You are unsure of the final bill | Wait for the exact amount if possible | Knowing the real cost can help avoid overborrowing. |
| You already need a loan to repay another loan | Compare alternatives first | Another loan may worsen the debt cycle. |
For smaller obligations like groceries, gas, prescriptions, or a partial bill, a $255 payday loan online same day or smaller loan may be enough. For larger or combined expenses, a $1,000 loan may reduce the need for multiple separate loan requests.
Risks of Borrowing Too Little
Borrowing too little can create problems if the loan does not fully cover the emergency. You may still miss the bill, face penalties, or need a second loan soon after the first one. That can increase total fees and make repayment harder.
Borrowing too little may be risky when:
- the emergency amount is already higher than $500
- you have several bills due at once
- you would need another loan immediately
- a second application would create more fees or repayment pressure
- the unpaid balance would create a serious consequence
Risks of Borrowing Too Much
Borrowing too much can also create unnecessary problems. A larger loan may mean higher total repayment, more fees, longer repayment, or larger scheduled payments. If you only need $500, borrowing $1,000 may increase debt without solving an additional urgent problem.
Borrowing too much may be risky when:
- the extra money would be used for nonessential spending
- the larger payment would strain rent, food, utilities, transportation, or insurance
- you are choosing the larger amount only because it is offered
- you do not understand the total repayment amount
- you are already managing other short-term debt
No-Credit-Check-Style Options
Borrowers with poor, limited, or thin credit may compare loans with no credit check when deciding between $500 and $1,000. These products may rely less on traditional credit review and more on income, identity, bank-account activity, state eligibility, and repayment ability.
No-credit-check-style does not mean no review, no verification, no cost, or guaranteed approval. Responsible lenders still need to decide whether the loan appears affordable.
| Potential Advantage | Potential Risk |
|---|---|
| May be available to borrowers with poor, thin, or limited credit history. | May carry higher APRs or fees than traditional personal loans. |
| May focus more on income, deposits, and bank-account activity. | Still requires verification and is not guaranteed. |
| May offer faster review than traditional bank lending. | Repayment may be short or difficult if it does not match your income schedule. |
Installment-Style vs. Payday-Style Repayment
Loan amount is only one part of the decision. Repayment structure can matter just as much. A $500 payday-style loan may be due quickly, while a $1,000 installment-style loan may be repaid through scheduled payments. However, the exact structure depends on the lender and product.
| Repayment Type | How It Usually Works | Main Consideration |
|---|---|---|
| Payday-style repayment | Often due quickly or near payday. | Can create pressure if the full amount is due at once. |
| Installment-style repayment | Repaid through scheduled payments over time. | May be easier to budget, but total repayment can rise if the term is longer or APR is high. |
| Cash advance structure | Usually a smaller short-term advance. | Useful for smaller gaps, but fees and due dates still matter. |
Tribal Loan Options
Some borrowers compare tribal loans online when mainstream payday-style or installment-style loans are not available. Tribal loans may have different legal structures, disclosures, governing law, repayment terms, and consumer-protection considerations than state-licensed loans.
Borrowers should review the final agreement carefully, including APR, fees, repayment schedule, lender identity, governing law, dispute-resolution terms, late-payment rules, and total repayment. A tribal loan may not be the lowest-cost option, so compare credit union loans, payment plans, installment loans, smaller cash advances, and local assistance programs before accepting.
Warning Signs of Risky Loan Offers
Emergency loan searches often attract risky lenders, lead generators, and scams. Be cautious with any offer that sounds too easy or avoids clear disclosures.
| Warning Sign | Why It Is Risky |
|---|---|
| Guaranteed approval for everyone | Responsible lenders still review income, identity, eligibility, and repayment ability. |
| Upfront fee before funding | Scammers may call it a processing, insurance, verification, or guarantee fee. |
| No clear lender or marketplace identity | You should know who is collecting your information and who is offering the loan. |
| Unclear APR, fees, or repayment schedule | You should understand the full cost before signing. |
| Pressure to borrow more than needed | A larger loan can increase repayment pressure and total cost. |
| Repeated refinancing encouragement | Renewals or repeat borrowing can keep fees growing. |
| Unusual payment requests | Gift cards, crypto, wire transfers, or payment apps are major red flags. |
Safer Alternatives to Compare Before Borrowing
Before accepting a $500 or $1,000 loan, compare options that may reduce cost, provide more time to repay, or avoid debt entirely.
- Credit union small-dollar loans: May offer lower-cost borrowing for qualified members.
- Provider payment plans: Medical providers, utility companies, repair shops, insurers, or landlords may split payments.
- Employer paycheck advance: Some employers or payroll providers offer early wage access.
- Nonprofit assistance: Local programs may help with rent, utilities, food, transportation, or emergency expenses.
- Borrowing less: A smaller amount may solve the emergency with less repayment pressure.
- Waiting one business day: If possible, a next-day option may be more manageable than the fastest high-cost offer.
How to Use a $500 or $1,000 Loan Responsibly
A small emergency loan should be used as a short-term tool, not a long-term borrowing habit. Responsible use starts before you accept the offer.
- Borrow only what you need.
- Review APR, fees, due dates, and total repayment before signing.
- Check that the payment date matches your income schedule.
- Use autopay only if funds will be available.
- Avoid taking multiple short-term loans at once.
- Keep copies of your agreement and payment confirmations.
- Contact the lender early if repayment trouble appears likely.
- Do not use emergency loans for nonessential purchases.
When a $500 Loan May Make Sense
A $500 loan may be reasonable when:
- the expense is urgent and necessary
- the amount needed is close to $500 or less
- you have income that can support repayment
- the payment fits your budget after essentials
- you understand APR, fees, due dates, and total repayment
- you have compared more than one option
- the loan helps avoid a more expensive consequence
When a $1,000 Loan May Make Sense
A $1,000 loan may be reasonable when:
- the emergency costs more than $500
- you need to cover several urgent bills at once
- a smaller loan would leave you needing another loan immediately
- the repayment schedule is clear and affordable
- you understand the full cost and due dates
- you are not borrowing extra for nonessential spending
When You Should Avoid Borrowing
A $500 or $1,000 loan may not be the right answer if it only delays a larger financial problem.
- You need a new loan to repay an old loan.
- The payment would leave no room for rent, food, utilities, transportation, or insurance.
- You do not understand the total repayment amount.
- The lender asks for money before funding.
- You feel pressured to sign immediately.
- The loan is for a nonessential purchase you cannot afford.
- A payment plan, assistance program, or lower-cost credit union option is available.
Why Borrowers Use EasyFinance.com
EasyFinance.com helps borrowers compare $500 and $1,000 emergency loan options from participating lenders in one place. Instead of applying through multiple unfamiliar websites, borrowers can review possible loan amounts, repayment timing, funding speed, loan structure, APR, fees, and total repayment more clearly.
As a BBB-accredited marketplace, EasyFinance.com provides a stronger trust signal while still making clear that final approval, loan terms, funding, servicing, and repayment come from the lender.
Borrowers can use EasyFinance.com to compare:
- $255 emergency loan options
- $500 cash advance options
- $1,000 emergency loan options
- payday-style loans
- installment-style loans
- small personal loan options
- bad-credit loan options
- no-credit-check-style products
Key Insights
- A $500 loan may be better for smaller emergencies, while a $1,000 loan may be better for larger or multiple urgent expenses.
- The best loan amount is usually the smallest amount that fully solves the emergency.
- Borrowing too little can lead to another loan, while borrowing too much can increase total repayment unnecessarily.
- Approval and same-day funding are not guaranteed, even when a lender offers fast online review.
- No-credit-check-style loans still require income, identity, bank-account activity, eligibility, and repayment review.
- EasyFinance.com is a BBB-accredited marketplace that helps borrowers compare online emergency loan options from participating lenders.
- Tribal loans may have different legal structures and should be reviewed carefully before acceptance.
- Borrowers should avoid upfront-fee requests, guaranteed-approval promises, unclear lender details, and pressure tactics.
FAQ
Which is easier to get: a $500 loan or a $1,000 loan?
A smaller loan may be easier to qualify for in some cases because the repayment obligation is lower, but approval depends on the lender, income, state availability, bank-account activity, identity verification, and ability to repay.
Can I get either loan without a credit check?
Some lenders may offer no-credit-check-style products that rely less on traditional credit review. These still require income, identity, eligibility, bank-account activity, and repayment review. Approval is not guaranteed.
How fast can I get the money?
Some approved borrowers may receive funds the same business day, next business day, or later depending on lender approval, verification, signed acceptance, cutoff times, funding method, and bank processing.
Is a $500 loan safer than a $1,000 loan?
A $500 loan may carry less repayment pressure if it fully solves the emergency. A $1,000 loan may be more practical if $500 would leave you needing another loan. The safer choice depends on total repayment and your budget.
What if I only need $300?
Borrowing less may be smarter if it fully covers the emergency. Some borrowers compare smaller products such as $255 payday loan options when they do not need the full $500.
Should I take a $1,000 loan even if I only need $500?
Usually no. Borrowing more than necessary can increase debt, fees, and repayment pressure. It is usually better to match the loan size to the actual emergency.
Does EasyFinance.com work with tribal lenders?
EasyFinance.com may help borrowers compare different online loan options, including some tribal loan options where available. Tribal loans may have different legal structures and should be reviewed carefully before acceptance.
What should I compare before accepting either loan?
Compare APR, fees, total repayment, payment dates, loan structure, funding timing, early payoff rules, late-payment consequences, and whether the payment fits your real budget.
Why use EasyFinance.com?
EasyFinance.com is a BBB-accredited marketplace that helps borrowers compare $500 and $1,000 emergency loan options from participating lenders in one place. Borrowers should still review the final lender agreement carefully before accepting any loan.
How do I start?
Start with EasyFinance.com, complete the online form, compare available offers, and review APR, fees, payment dates, funding speed, and total repayment before accepting any loan.
Related Articles
- $500 Loan Online: How to Get Approved Fast in 2026
- Guaranteed Approval $500 Loans: What’s Real and What’s Hype
- No Credit Check $500 Loans: Your Options Explained
- Same Day $500 Loan for Emergencies: Complete Guide
- Best $500 Loan Offers Online: Compare Lenders and Rates
- Can I Get a $500 Loan With Bad Credit?
- Do I Need Collateral for a $500 Loan?
- What APR to Expect on a $500 Loan in 2026
- How Fast Can I Get a $500 Loan Deposited in My Bank Account?
- Are $500 Payday Loans Safer Than Online Installment Loans?
- Best Alternatives to a $500 Loan: Credit Cards, Borrowing Apps, and Advances
- $500 Loan vs $1000 Loan: Which Is Better for Emergencies?
- $500 Payday Loan vs $500 Installment Loan: Which Costs Less?
- Cash Advance vs $500 Online Loan: What’s the Difference?
- $500 Loan from a Bank vs Direct Lender: Pros and Cons
- $500 Loan Online in Texas: Rules and Options
- How to Get a $500 Loan in California with No Credit Check
- Best $500 Loan Options in Florida for 2026
- Can You Get a $500 Loan Same Day in New York?
- When Should You Use a $500 Loan for Bills and Expenses?
- Smart Ways to Repay a $500 Loan Without Extra Fees
- The Risks of Relying on $500 Payday Loans Too Often
- How to Budget After Taking a $500 Loan
- Emergency Situations Where a $500 Loan Makes Sense

 EasyFinance Blog
 Twitter
 Facebook
 Google+
 LinkedIn
 Email Subscriptions
